
I’m on holiday this week and hadn’t planned on writing anything this morning. But between Cagliari’s start to the season and what’s about to happen at the Fed (and the BoJ, for that matter), the circumstances struck me as exceptional enough to warrant a few lines anyway.
As I write this, interest rates aren’t the only thing sitting at levels younger generations have never seen. Cagliari Calcio is too. Four matches, three wins (including a deserved and emphatic away win over Atalanta this weekend), nine points, and a provisional 4th place in Serie A. As for the real front page, worth a detour to last Friday’s Le Temps (page 20), with a long profile of Alessandro Romano, the young Italian-Swiss midfielder currently plying his trade at… Cagliari. Link here.
On to the actual news. Last week’s US inflation print came in broadly as expected, and markets now assign a high probability to a Fed hike this week. The move owes more to the recent rebound in energy prices, but it’s worth flagging that the more “structural” core services inflation is still running near 3% (3.1% in August).
There’s clearly a lot happening behind closed doors at the FOMC, and Chair Warsh’s Jackson Hole speech seems to have bought him a few extra “hawkish” votes. The trouble is the midterms are under two months away, and hiking on a divided Fed isn’t the kind of “poor” consensus a Fed chair wants walking into an election. If Warsh can’t get to nine or ten votes this meeting, he almost certainly can’t hike at the October 27-28 meeting either, one week before the vote. Rock, meet hard place.
My take: if they don’t hike, long rates go up anyway, and the market starts asking out loud whether the Fed is actually serious about inflation. At the very least, they could stop growing the balance sheet. Warsh needs to get ahead of this now, or the credibility gap starts writing its own headlines and the catch-up hike that follows is always more painful than the one you didn’t dodge.
It’s much the same story on the other side of the Pacific. The BoJ meets right on the Fed’s heels this week, and Governor Ueda needs to turn genuinely restrictive now, in substance, not just in tone, or he risks watching the yen resume its slide while long JGB yields climb even further. Talking about upside risks to inflation only buys credibility for so long; markets have already shown this year that they’ll keep testing any central bank that hesitates to act on what it says.
So: I expect a Fed hike, and I’m hoping (praying, even) that long rates ease back down. Markets already have plenty to be nervous about: inflation, stronger-than-expected growth on the back of AI capex and subsequent rising debt, a rising term premium and that’s before factoring in a fiscal outlook that looks a little worse every time Trump, Bessent and the rest of the administration open their mouths. In that context, the Fed doesn’t just need to talk tough on credibility, it needs to prove it. Short term, that’s probably not great news for equities, but better safe than sorry. If they don’t deliver, the dollar heads south while gold and long rates take off.
Which brings me back to Cagliari. A club with a fraction of the resources of Italy’s giants is currently playing like a top-flight side because it does the basics right, week after week. The US is not Cagliari: it’s supposed to be Juventus, Milan and Inter rolled into one, the reigning economic superpower with the deepest bench in the world. And yet, every hesitation on rates, every quarter of runaway deficits, makes it look a little more like a 2nd zone EM economy or a club fighting to avoid the drop than one defending its title. Superpowers don’t get relegated because they lose one match. They get relegated when they stop playing like one for long enough. Something for Warsh, Bessent, Trump and for the rest of Washington, to keep in mind.
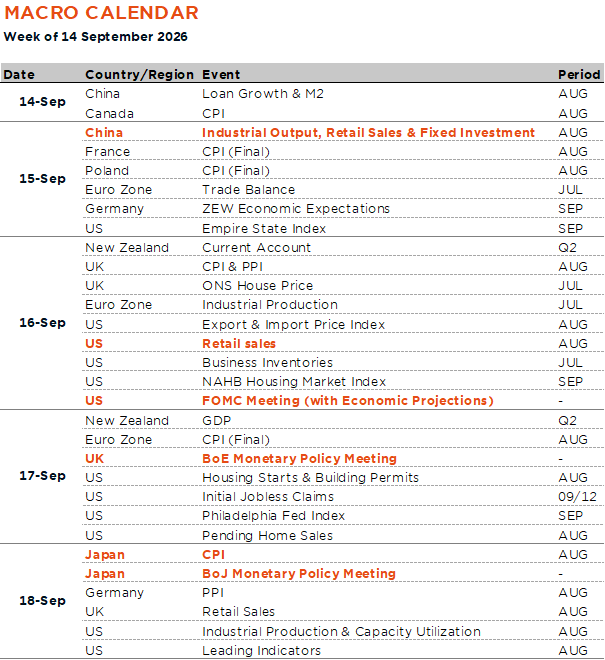
Economic Calendar
This is a marketing communication issued by DECALIA SA. It is neither directed to, nor intended for distribution or use by, any person or entity who is a citizen or resident of or located in any locality, state, country or jurisdiction where such distribution, publication, availability or use would be contrary to law or regulation. The information and data presented in this document are not to be considered as an offer or invitation to buy or sell any securities or financial instruments nor to subscribe to any services. The information, opinions, estimates, calculations etc. contained in this document reflect a judgment at the original date of publication and are subject to change without notice. Investments in any securities or financial instruments may not be suitable for all recipients and may not be available in all countries. This document has been prepared without taking account of the objectives, financial situation or needs of any particular investor. Before entering into any transaction, investors should consider the suitability of the transaction to individual circumstances and objectives. Any investment or trading or other decision should only be made by the client after a thorough reading of the relevant product term sheet, subscription agreement, information memorandum, prospectus or other offering document relating to the issue of the securities or other financial instruments. Where a document makes reference to a specific research report, the document should not be read in isolation without consulting the full research report, which may be provided upon request.